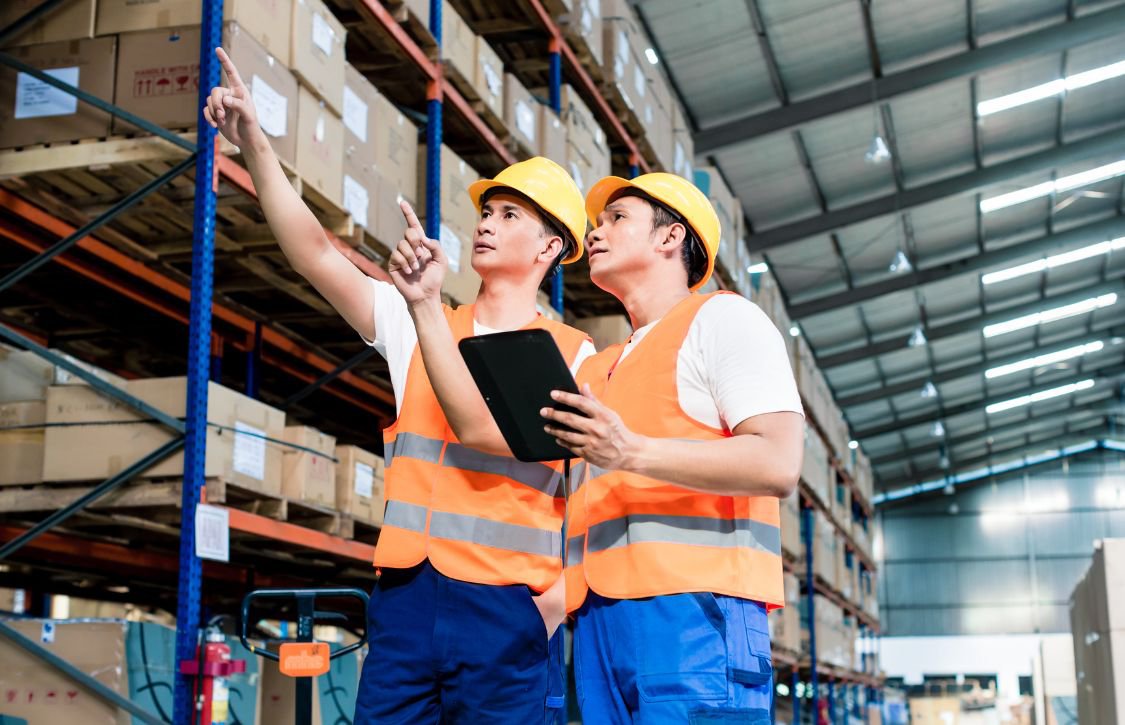
A forklift that was physically retired two years ago shouldn't continue aging on the company ledger. Otherwise, it will inflate the owner’s net asset value and misstate annual expenses on every financial statement. Meanwhile, an RF scanner purchased through an operating budget and left off the books functions on the warehouse floor while remaining a blind spot to accounting. Fixed asset reconciliation catches both errors by aligning what the financial ledger says with what actually sits in the facility. For CFOs and controllers at large third-party logistics (3PL) providers, this reconciliation maintains depreciation accuracy, supports clean audits, and prevents capital misallocation across multi-facility operations.
What Fixed Asset Reconciliation Solves in Logistics
Ghost, unrecorded, and misclassified assets represent three distinct reconciliation failures that accumulate when records go unchecked. Ghost assets sit on the books but no longer exist physically. Unrecorded assets operate on the floor but were never capitalized. Misclassified assets carry incorrect category codes, locations, or useful life assumptions that distort every depreciation calculation they feed.
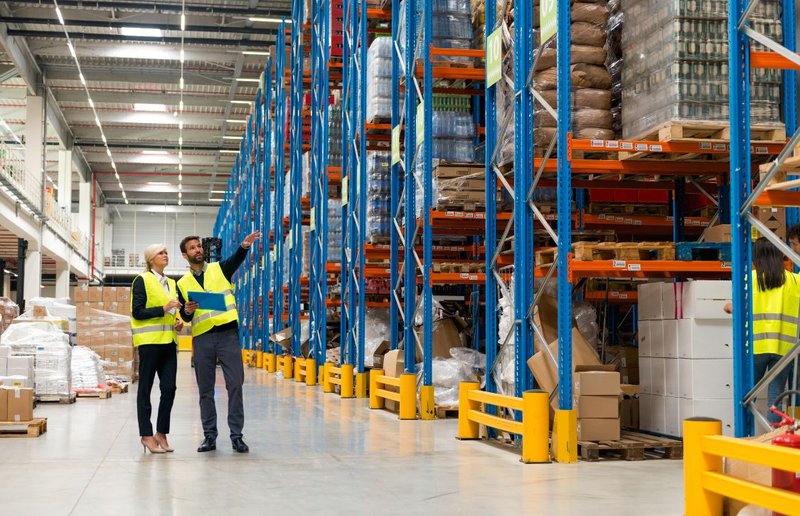
The core discipline requires aligning three records simultaneously: what assets exist on the warehouse floor, what the fixed asset register reports, and what the general ledger carries. Each discrepancy type demands a different correction. Ghost assets need write-offs. Unrecorded assets need capitalization entries. Misclassifications need reclassification with updated depreciation schedules. Procurement teams evaluating 3PL partners should treat fixed asset reconciliation practices as a due diligence item. A provider that can't account for its own equipment raises questions about operational discipline across every other process in the facility.
Running a Fixed Asset Reconciliation in a Warehouse Environment
During physical verification, audit teams walk the facility, scan barcoded asset tags, and compare results against the fixed asset register. Radio Frequency Identification (RFID) tagging accelerates this process in large warehouse environments by auto-populating the reconciliation file as the team moves through each zone. WERC's DC Measures benchmarking program tracks operational accuracy metrics that depend directly on this type of physical-to-system alignment across distribution center operations.
For companies still resistant to modern warehousing, manual methods can cause problems during the audit. Spreadsheet-based tracking introduces errors and goes stale between verification cycles. This is especially problematic for organizations managing thousands of assets across multiple sites. Centralized asset management platforms address this by maintaining a live register that updates as assets move, depreciate, or retire.
Monthly fixed asset reconciliation cadence catches discrepancies before they compound into material variances. A quarterly cycle misses three months of asset additions, transfers, and disposals. By the time the next count occurs, the gap between the register and the floor has widened enough to require significant adjustment entries.
How Reconciliation Supports Depreciation and Tax Accuracy
A misclassified forklift depreciating over ten years instead of seven understates annual expense and overstates net asset value. Across a fleet of dozens of units, these individual errors compound into a material misstatement that affects both financial reporting and tax positions.
Asset-based 3PLs with owned truck fleets, material handling equipment, and warehouse infrastructure carry depreciation profiles that vary significantly by asset class. Fixed asset reconciliation ensures each asset depreciates under the correct method and useful life assumption per Modified Accelerated Cost Recovery System (MACRS) guidelines.
The Internal Revenue Service’s Publication 946 governs how businesses recover the cost of tangible property through depreciation, including Section 179 expensing elections and bonus depreciation provisions. An unreconciled fixed asset register produces unreliable inputs for these calculations. Auditors testing fixed asset balances expect a clean trail from physical verification through the general ledger. They will test that trail against the depreciation methods and useful life assignments the register reports.
Fixed Asset Reconciliation as an Operational Discipline
A reconciliation activity that flags 15 scanners as missing from a single facility reveals device management failures that affect picking accuracy, cycle count reliability, and overall floor productivity. This operational intelligence surfaces only when someone compares the register against what's actually in the building.
ISO 9001 certification requires documented, auditable processes for anything that affects operational quality. Every forklift, every rack, and every scanner directly impacts warehouse throughput and service delivery. Keeping the fixed asset register accurate ensures that capital planning, maintenance scheduling, and equipment replacement decisions reflect actual floor conditions rather than outdated book entries.
Asset-based providers that own their full infrastructure control the equipment lifecycle from acquisition through disposal. Clean asset records support better capital budgeting, sharper maintenance cycles, and financial reporting that auditors can verify without extended fieldwork.
Every unreconciled asset on the register either inflates or understates the balance sheet. Contact us to learn how asset-based logistics infrastructure and certified processes keep your operations audit-ready year-round.
Comments are closed